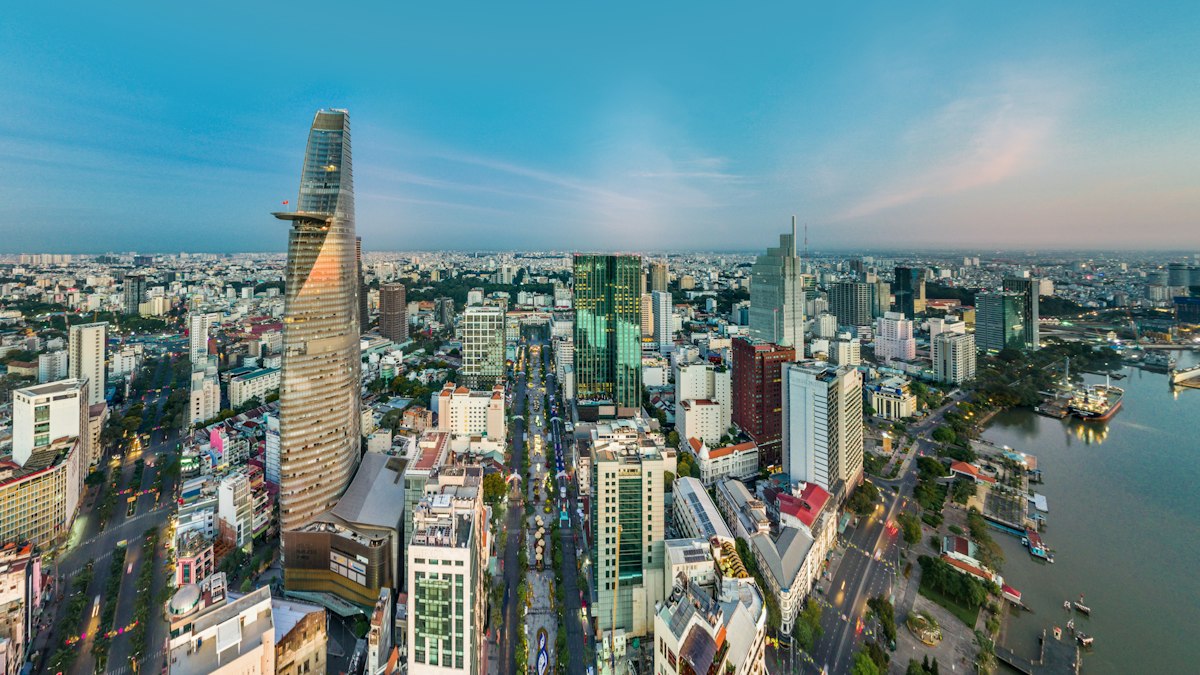
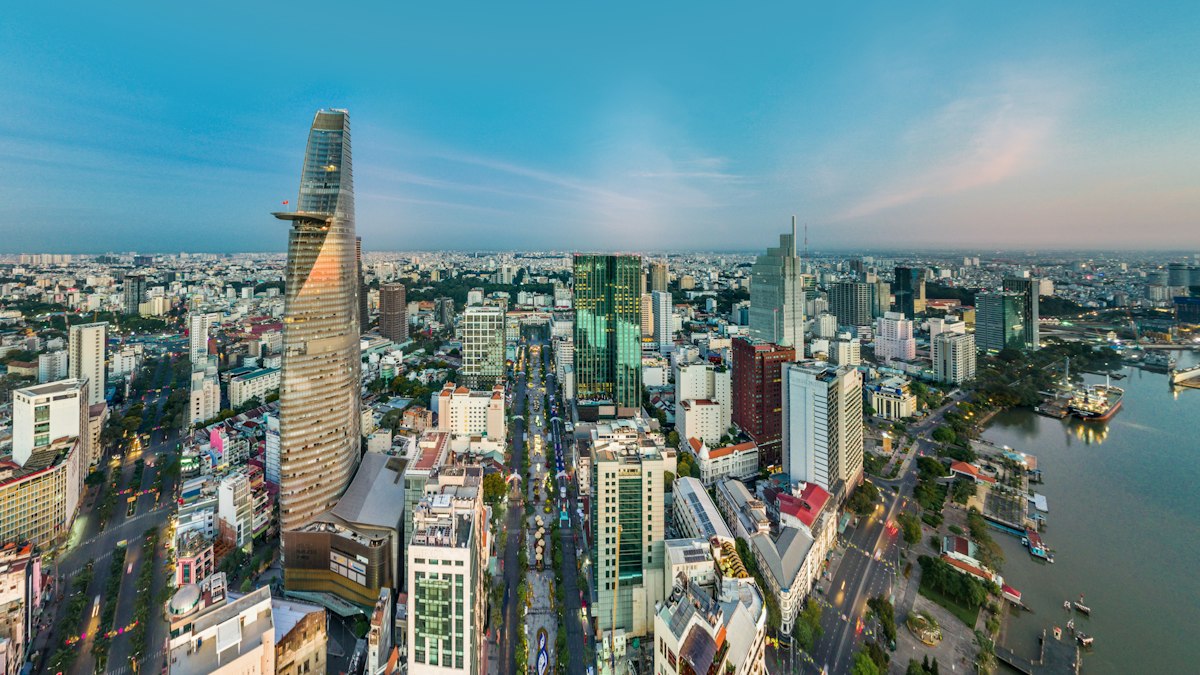
For sponsors and commercial lenders structuring Vietnamese infrastructure and energy deals, multilateral co-financing Vietnam arrangements have become a defining feature of bankability. When the Asian Development Bank (ADB), the International Finance Corporation (IFC), or the World Bank Group (IBRD/IDA) sits alongside commercial banks in a financing package, the deal gains preferred creditor protection, a disciplined environmental and social (E&S) overlay, and a signaling effect that lowers perceived country and sector risk.
But these benefits come with structural trade-offs — cross-default triggers, negative pledge constraints, and permitting layers that commercial counsel must map before term sheets are signed. This article sets out the practical legal architecture of multilateral co-financing in Vietnam, from parallel and joint structures to B-loan syndication and IFC Performance Standards compliance.
Table of Contents
- 1. Why Multilateral Co-Financing Matters for Vietnamese Projects
- 2. Parallel vs. Joint Co-Financing Structures
- 3. ADB Co-Financing Framework in Vietnam
- 4. The IFC B-Loan Syndication Program
- 5. World Bank IBRD/IDA Instruments for Vietnam
- 6. Preferred Creditor Status Explained
- 7. Cross-Default and Negative Pledge Implications
- 8. Environmental and Social Standards Overlay
- 9. Interface with Local Permitting and Licensing
- 10. Structuring Considerations for Vietnamese Deals
- Frequently Asked Questions
1. Why Multilateral Co-Financing Matters for Vietnamese Projects
Vietnam’s infrastructure and energy pipeline — ports, toll roads, LNG-to-power plants, offshore wind, and grid upgrades — requires capital well beyond what domestic banks can prudently lend given single-borrower exposure limits. Multilateral co-financing Vietnam structures solve this by combining a multilateral development bank’s (MDB) own-account tranche with commercial lender participation, often arranged through the MDB’s syndication desk.
The presence of ADB, IFC, or the World Bank signals to rating agencies and commercial banks that the project has passed a rigorous due diligence and E&S screening process, which in turn can reduce the credit spread demanded by participating commercial lenders.
1.1 The Sponsor’s Perspective
For a project sponsor, multilateral co-financing Vietnam deals typically mean longer tenors, more predictable covenant packages, and access to political risk mitigation that a purely commercial syndicate cannot offer. The trade-off is a longer appraisal timeline and a binding commitment to IFC Performance Standards or equivalent ADB safeguard requirements throughout construction and operation.
1.2 The Commercial Lender’s Perspective
Commercial lenders participating through B-loan or parallel facilities gain comfort from preferred creditor status and from the MDB’s ongoing supervision role, but must accept intercreditor terms that subordinate certain enforcement rights to the lead MDB during the life of the facility.
2. Parallel vs. Joint Co-Financing Structures
Two structural models dominate multilateral co-financing Vietnam transactions: parallel co-financing and joint co-financing. Understanding which model applies determines the governing documentation, the security package, and how cross-default provisions are drafted.
2.1 Parallel Co-Financing
In a parallel structure, each multilateral lender (and any commercial co-lender) enters a separate loan agreement with the borrower, each tranche secured independently but typically under a common security and intercreditor framework. Disbursement, repayment, and default remedies run on separate but coordinated schedules. This is the more common structure for Vietnamese power and transport projects involving ADB alongside commercial banks, because it preserves each lender’s direct contractual relationship with the project company while still allowing coordinated security enforcement.
2.2 Joint Co-Financing
In a joint structure, the MDB acts as lender of record for the full syndicated amount — including the participations sold down to commercial banks under a B-loan or similar arrangement — and the commercial participants hold a contractual (not direct) claim against the borrower. This is the structural basis of the IFC B-loan program described below, and it is the mechanism through which commercial lenders inherit preferred creditor status benefits indirectly.
2.3 Choosing Between the Two
The choice is rarely left to the borrower alone; it follows from which MDB leads the financing and which instrument it uses. IFC virtually always uses the joint/B-loan model; ADB and the World Bank more frequently use parallel co-financing when multiple official lenders are involved, reserving syndicated participations for separate commercial tranches.
3. ADB Co-Financing Framework in Vietnam
ADB co-financing in Vietnam operates through both official co-financing (with bilateral agencies, export credit agencies, and other MDBs) and commercial co-financing (through its Complementary Financing Scheme and direct value-added products such as Partial Credit Guarantees). ADB has financed Vietnamese transmission, renewable energy, and urban infrastructure projects on a sovereign and non-sovereign basis, with sovereign-guaranteed loans flowing through the State Bank of Vietnam and the Ministry of Finance, and non-sovereign operations lending directly to project companies.
3.1 ADB Non-Sovereign Operations
Non-sovereign ADB lending is the relevant category for most privately sponsored infrastructure and energy deals. ADB’s Private Sector Operations Department structures these loans with covenant packages, step-in rights, and security arrangements closely comparable to international project finance market practice, while layering in ADB’s own safeguard policy requirements.
3.2 Complementary Financing Scheme
Under its Complementary Financing Scheme, ADB sells down loan participations to commercial banks and institutional investors while remaining lender of record, extending preferred creditor status treatment to the participating lenders in a manner functionally similar to the IFC B-loan program.
4. The IFC B-Loan Syndication Program
The IFC B-loan program is among the oldest and most tested multilateral co-financing Vietnam tools available to commercial banks seeking exposure to Vietnamese projects without taking on direct sovereign or emerging-market structuring risk. IFC lends its own funds as the “A-loan” and simultaneously arranges a syndicated “B-loan,” in which commercial banks and institutional investors participate as risk participants rather than as lenders of record.
4.1 A-Loan / B-Loan Mechanics
IFC remains the lender of record for both tranches, meaning the borrower contracts only with IFC; B-loan participants hold a participation agreement with IFC rather than a direct claim against the Vietnamese borrower. This structure is what extends IFC’s preferred creditor status, and the associated withholding tax and currency convertibility protections, to the commercial participants.
4.2 Pricing and Tenor Benefits
Because B-loan participants benefit indirectly from IFC’s standing with the Government of Vietnam, pricing on B-loan tranches in Vietnamese energy and infrastructure deals has historically been tighter, and tenors longer, than a comparable standalone commercial facility to the same borrower.
4.3 The Parallel Loan Alternative
IFC also offers a parallel loan structure for commercial lenders unwilling to take indirect participation risk on IFC itself; this preserves a direct lender-borrower relationship but forgoes the full preferred creditor status pass-through enjoyed under the B-loan model.
5. World Bank IBRD/IDA Instruments for Vietnam
World Bank IBRD IDA Vietnam engagement has shifted over the past decade as Vietnam graduated from IDA concessional eligibility toward IBRD terms, reflecting its middle-income status. For project sponsors, the relevant instruments are now predominantly sovereign-guaranteed IBRD loans for public infrastructure, alongside IFC (the Bank Group’s private-sector arm) for privately sponsored projects, and MIGA guarantees for political risk cover on commercial lending.
5.1 Sovereign-Guaranteed Lending
IBRD loans to Vietnam typically require a sovereign guarantee from the Ministry of Finance, making them most relevant to publicly procured infrastructure (grid expansion, urban transit, water and wastewater) rather than privately financed independent power producer or toll road structures.
5.2 MIGA Political Risk Guarantees
Where commercial lenders co-finance alongside the World Bank Group on a private deal, MIGA guarantees covering currency transfer restriction, expropriation, and breach of contract risk are frequently layered onto the commercial tranche, improving its risk profile without the lender itself holding preferred creditor status.
6. Preferred Creditor Status Explained
Preferred creditor status is the informal (not treaty-based, in most cases) practice by which sovereign governments, including Vietnam, prioritize repayment obligations to MDBs such as ADB, IFC, and the World Bank ahead of other external creditors, reflecting these institutions’ role in maintaining access to future development finance. It is not a legal priority ranking enforceable in Vietnamese courts, but a reputational and relationship-based practice that has historically held even during periods of balance-of-payments stress.
6.1 Scope and Limits
Preferred creditor status in a multilateral co-financing Vietnam transaction typically extends to the MDB’s own A-loan and, through B-loan or parallel co-financing participation agreements, to commercial participants — but counsel should confirm, deal by deal, exactly which tranches and which lenders the status is understood to cover, since it is a matter of practice rather than codified Vietnamese law.
6.2 Practical Value for Commercial Lenders
For a commercial bank, preferred creditor status reduces perceived convertibility and transfer risk and is frequently cited by credit committees as a basis for more favorable internal risk ratings on Vietnamese exposure arranged through a B-loan or parallel structure.
7. Cross-Default and Negative Pledge Implications
Multilateral facility agreements typically include broad cross-default clauses that treat a default under any other financing of the borrower (or, in some drafting, of the sponsor group) as a default under the multilateral facility itself, and negative pledge covenants restricting the borrower from granting security to other creditors without MDB consent. These provisions have direct consequences for how commercial lenders structure parallel or subsequent financings.
7.1 Cross-Default Drafting in MDB Facilities
Because ADB, IFC, and World Bank Group facility agreements are drafted against a global template, Vietnamese counsel must carefully reconcile cross-default definitions with local financing documents, particularly where a project company also holds domestic VND working-capital facilities that were not contemplated when the MDB facility was negotiated.
7.2 Negative Pledge and Local Security Registration
Negative pledge covenants interact with Vietnam’s secured transactions registration regime; subsequent domestic lenders must confirm, through the national registry, that proposed security does not breach an existing MDB negative pledge before perfecting their own interest, and intercreditor deeds should expressly address permitted security carve-outs.
7.3 Intercreditor Coordination
A well-drafted intercreditor agreement in a multilateral co-financing Vietnam deal will reconcile the MDB’s cross-default and negative pledge rights with any later domestic facilities, typically through standstill periods and consent thresholds negotiated at financial close rather than left for a subsequent amendment.
Structuring a co-financed project in Vietnam? IVLF Advisors advises sponsors, commercial lenders, and multilateral institutions on the legal structuring of ADB, IFC, and World Bank co-financed infrastructure and energy transactions in Vietnam. Contact our project finance team for a confidential preliminary consultation on your transaction.
8. Environmental and Social Standards Overlay
Every MDB-financed project in Vietnam carries an environmental and social due diligence overlay that sits alongside, and is frequently more demanding than, domestic environmental licensing requirements. IFC Performance Standards are the most widely referenced E&S framework in Vietnamese project finance, having been adopted directly or by reference by most commercial banks applying the Equator Principles to their own lending.
8.1 Overview of the IFC Performance Standards
The eight IFC Performance Standards cover environmental and social risk assessment and management, labor and working conditions, resource efficiency and pollution prevention, community health and safety, land acquisition and resettlement, biodiversity conservation, indigenous peoples, and cultural heritage. ADB and the World Bank apply their own, broadly comparable safeguard policies, and most syndicate lenders require the project company to comply with whichever standard is more stringent.
8.2 Environmental and Social Action Plans
Projects typically operate under a binding Environmental and Social Action Plan (ESAP) agreed with the lead MDB, with periodic independent monitoring reports required as a condition of continued disbursement — a covenant structure Vietnamese sponsors should budget for from the earliest feasibility stage.
9. Interface with Local Permitting and Licensing
The E&S overlay imposed by multilateral lenders does not replace Vietnamese environmental licensing — it sits on top of it, and the two regimes must be reconciled in the project’s compliance calendar.
9.1 Reconciling the EIA Process with IFC Performance Standards
Vietnam’s domestic environmental impact assessment (EIA) process, administered under the Law on Environmental Protection, does not always map directly onto the scope of IFC Performance Standards, particularly around resettlement, biodiversity offsets, and cumulative impact assessment, creating a gap that project counsel must close through supplementary studies commissioned specifically for the lenders.
9.2 Sequencing Permits Around Lender Conditions Precedent
Because disbursement conditions precedent typically require both the domestic EIA approval and lender sign-off on the supplementary E&S studies, sponsors should sequence permitting applications early enough that neither workstream becomes the critical path to financial close.
10. Structuring Considerations for Vietnamese Deals
Sponsors evaluating multilateral co-financing Vietnam structures should weigh the benefits of preferred creditor status, longer tenors, and E&S credibility against the longer appraisal timelines, more intensive covenant monitoring, and the need to reconcile MDB documentation with Vietnamese law on security, foreign exchange, and cross-border lending registration.
10.1 Aligning MDB Templates with Vietnamese Law
MDB facility agreements are drafted under English or New York law concepts that require careful adaptation to Vietnamese security law, foreign loan registration with the State Bank of Vietnam, and enforcement mechanics, and early legal input materially shortens the negotiation cycle.
10.2 Selecting the Right Co-Financing Instrument
The right choice between an ADB parallel facility, an IFC B-loan program participation, or a World Bank/MIGA-backed structure depends on the project’s ownership, sector, and risk profile, and should be tested against term sheets from more than one institution before a lead arranger is selected.
Further background on co-financing frameworks is available from the Asian Development Bank’s co-financing program page and the IFC Syndicated Loans / B-Loan Program overview.
Frequently Asked Questions
What is multilateral co-financing in a Vietnamese infrastructure project?
It is a financing structure where ADB, IFC, or the World Bank lends alongside commercial banks, either through parallel loan agreements or joint structures such as IFC’s B-loan program.
Does preferred creditor status apply to commercial lenders too?
Through B-loan or parallel co-financing participations, commercial lenders can benefit indirectly from the lead MDB’s preferred creditor status, though this is a market practice, not a Vietnamese statutory right.
How do IFC Performance Standards affect local permitting?
They impose E&S requirements beyond Vietnam’s domestic EIA process, so sponsors typically commission supplementary studies to satisfy both the regulator and the lenders.
What is the difference between an A-loan and a B-loan?
The A-loan is IFC’s own-account tranche; the B-loan is syndicated to commercial banks, which hold a participation in IFC’s loan rather than a direct claim on the borrower.
Why do negative pledge clauses matter for later domestic financing?
They can restrict a borrower from granting security to subsequent domestic lenders without MDB consent, so later facilities must be checked against the existing negative pledge before closing.
Sponsors and lenders approaching a multilateral co-financing Vietnam transaction should commission an early legal mapping of the proposed MDB instrument against Vietnamese security, foreign exchange, and environmental permitting requirements before finalizing term sheets. For transaction-specific structuring advice, speak with IVLF Advisors’ project finance team, and review our broader banking and finance advisory services.
This article provides general information on multilateral co-financing structures in Vietnam and does not constitute legal, tax, or financial advice. Sponsors and lenders should seek transaction-specific advice before relying on any of the structures described.
This article is provided for general information only and does not constitute legal advice for any specific case. Regulations may change – please consult a qualified professional before acting. Should further analysis be required, please contact one of our lawyers below.