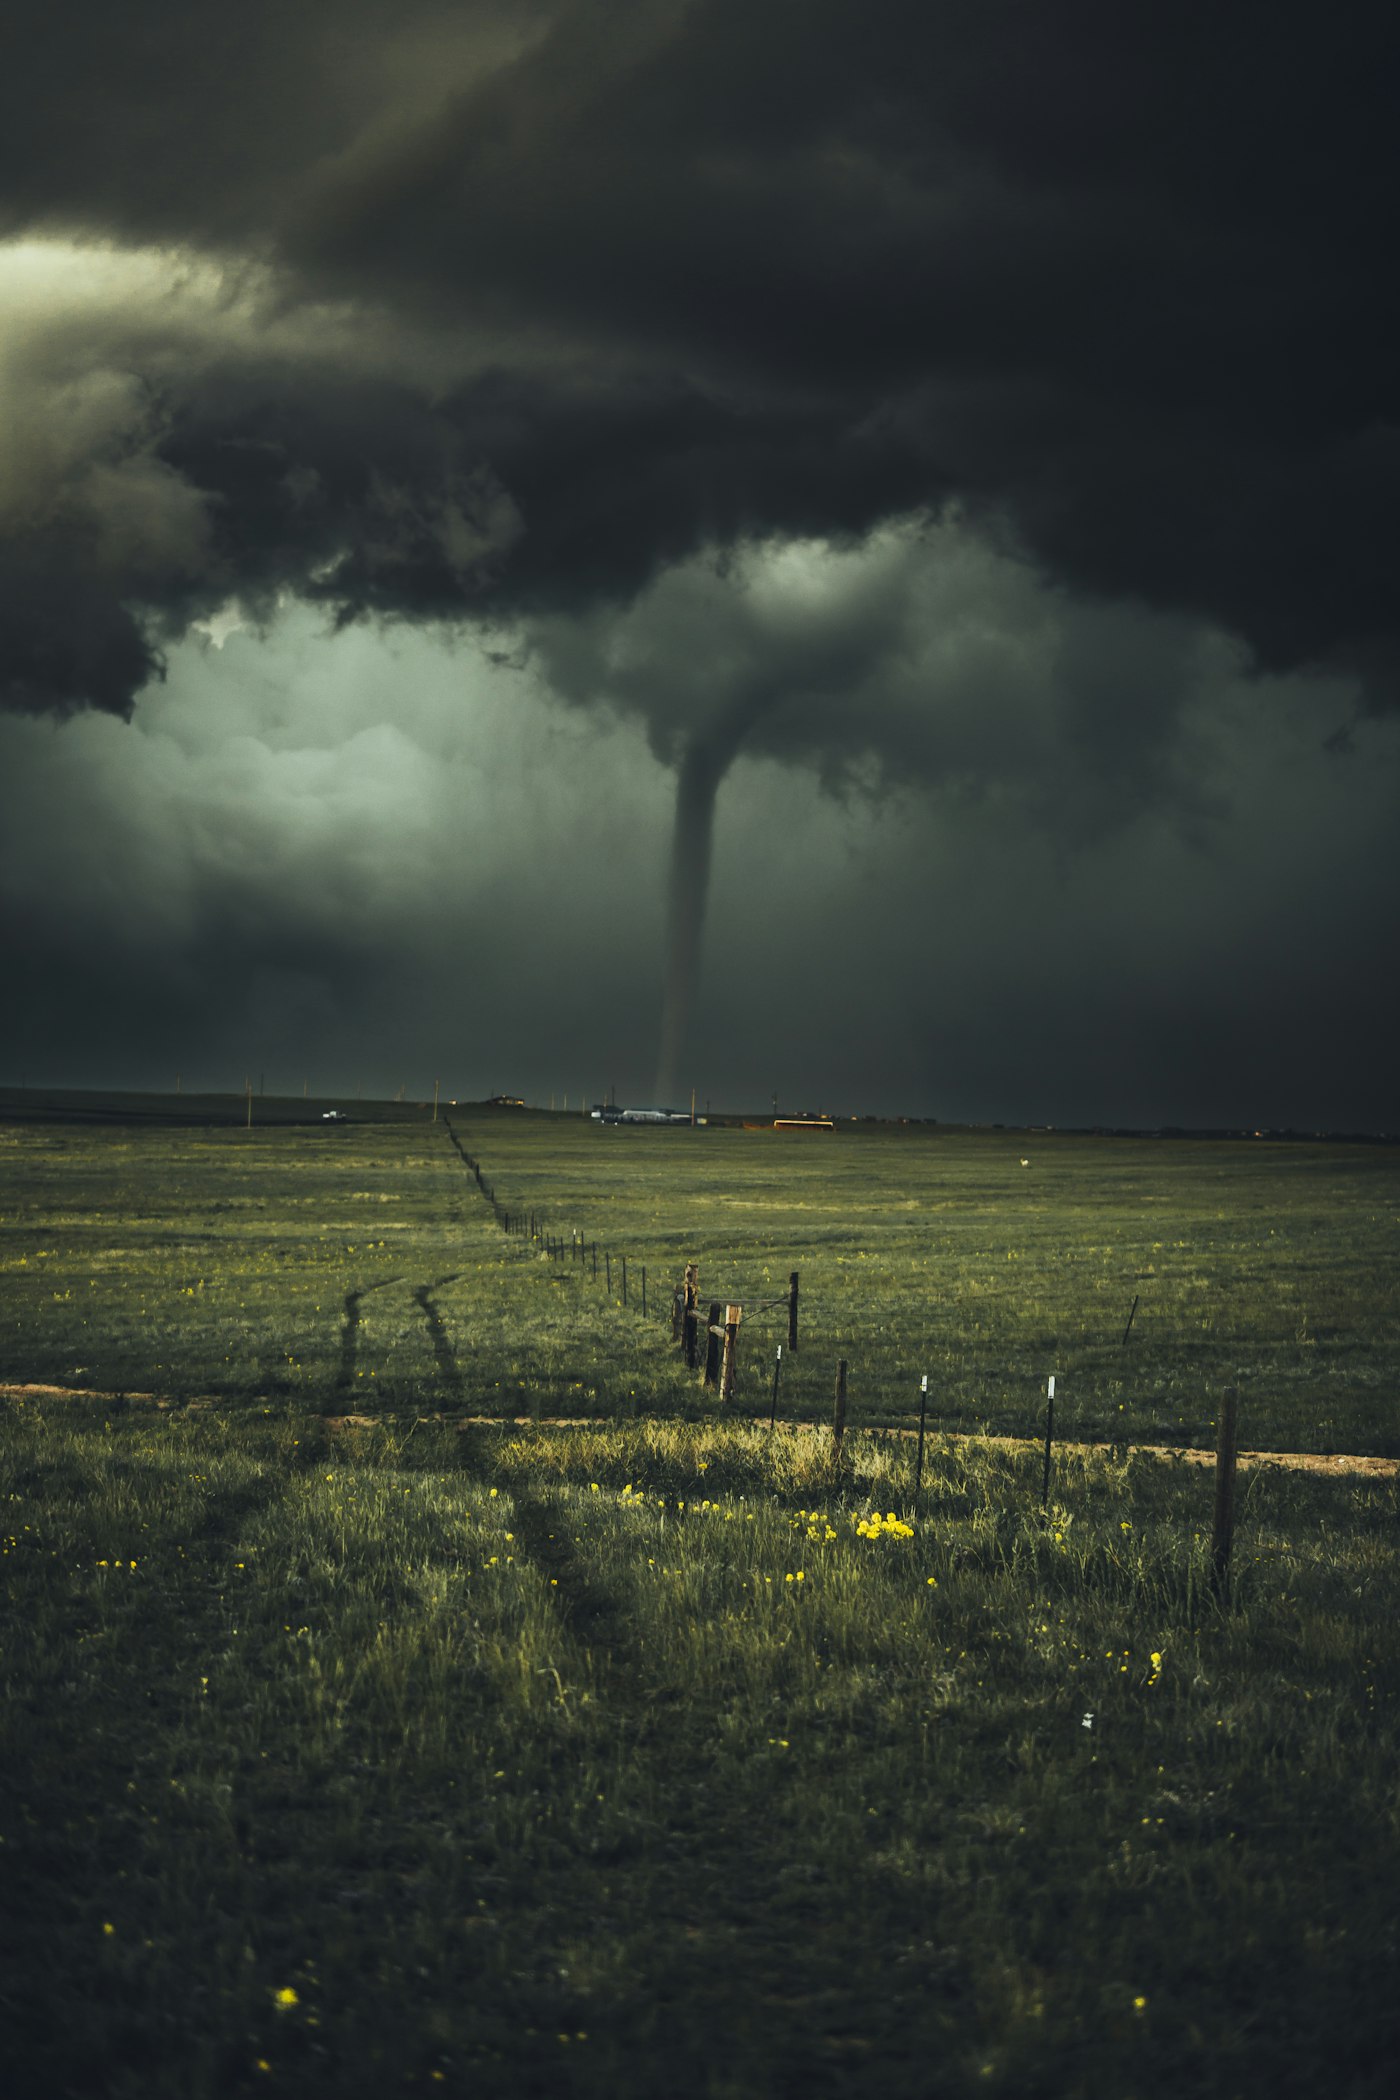
Vietnam’s coastline absorbs a typhoon season every year, and its northern and central provinces face recurring flood losses that insurers and reinsurers price into every commercial policy. Structuring around a Vietnamese regulatory and FX gap by using an offshore vehicle is a recurring theme in cross-border risk transfer generally; see IVLF’s guide to green securitization and ESG ABS structures in Vietnam.
Insurance-linked securities Vietnam, the catastrophe bonds and parametric instruments that let capital markets absorb exactly this kind of risk, are a natural fit for that exposure profile. They are also, as of today, not issuable directly out of Vietnam, and understanding exactly why is the first step toward structuring around the gap rather than waiting for it to close.
1. Why Insurance-Linked Securities Vietnam Cannot Be Issued Domestically Today
A catastrophe bond requires a special purpose reinsurance vehicle capable of assuming risk from a ceding insurer, issuing rated or unrated notes to capital markets investors, and paying claims automatically upon a defined trigger event, whether an indemnity-based loss threshold or a parametric trigger such as a measured wind speed or seismic magnitude.
Insurance-linked securities Vietnam transactions of this kind require a regulatory framework for special purpose reinsurance vehicles that Vietnam’s insurance law does not currently provide. The Law on Insurance Business, as it stands, is built around licensed insurers and reinsurers conducting traditional risk-bearing activity, not around a bankruptcy-remote, single-transaction vehicle designed purely to intermediate risk transfer to capital markets.
Without that vehicle type, insurance-linked securities Vietnam issuance domestically is not simply difficult; it lacks a legal chassis to attach to. This is a materially different starting point from securitization of loan receivables, where at least general Civil Code assignment principles offer a foundation to build on, however incomplete.
Comparative context helps frame the scale of the gap. Markets such as Mexico, the Philippines, and several Caribbean nations have successfully sponsored catastrophe bonds covering sovereign or quasi-sovereign natural disaster exposure, typically working through the World Bank’s capital markets platform or a similar multilateral intermediary rather than building purely private domestic infrastructure from scratch. Insurance-linked securities Vietnam sponsors, whether private insurers or eventually a sovereign disaster risk pool, could plausibly follow a similar multilateral-intermediated path rather than waiting for standalone domestic legislation, since a multilateral platform can supply much of the offshore vehicle and documentation infrastructure that Vietnam’s market currently lacks.
2. Offshore SPV Structuring as the Practical Workaround
Given the domestic gap, insurance-linked securities Vietnam risk transfer in practice today means routing the transaction through an offshore special purpose reinsurance vehicle, typically domiciled in Bermuda, the Cayman Islands, or Singapore, jurisdictions with established catastrophe bond issuance infrastructure and regulatory frameworks purpose-built for this activity.
A Vietnamese ceding insurer would enter into a reinsurance or retrocession agreement with the offshore vehicle, which then issues notes to international investors, with claims paid based on Vietnam-specific triggers, whether indemnity losses at the ceding insurer or a parametric index tied to Vietnamese meteorological or seismic data.
Structuring insurance-linked securities Vietnam this way raises immediate foreign exchange control questions.
Premium payments flowing offshore to the reinsurance vehicle, and claims payments flowing back onshore following a triggering event, both require careful structuring under Vietnam’s foreign exchange management framework, since cross-border reinsurance payments of this kind and scale are not a routine, pre-cleared transaction category for most Vietnamese insurers.
3. Regulatory and Foreign Exchange Barriers in Detail
Foreign exchange control is not a footnote for insurance-linked securities Vietnam structuring; it is often the binding constraint.
Vietnamese insurers ceding risk offshore under a catastrophe bond structure need to confirm that premium outflows qualify under permitted reinsurance payment categories, and that any large, contingent claims payment received from an offshore vehicle following a catastrophic event can be repatriated without triggering additional regulatory review at the worst possible moment, immediately after a major loss event when speed of payment matters most to policyholders.
Separately, State Securities Commission oversight of any securities-like instrument marketed to or through Vietnamese counterparties adds a further compliance layer, even where the notes themselves are issued entirely offshore and never directly offered to Vietnamese investors.
Insurance-linked securities Vietnam structures should be built with Vietnamese counsel confirming, at each step, that the onshore ceding insurer’s participation does not inadvertently trigger securities offering rules under the Securities Law 2019 that were not designed with catastrophe risk transfer in mind.
4. Parametric Triggers Suited to Vietnam’s Catastrophe Exposure
Parametric triggers, which pay out based on an objectively measured physical event rather than adjusted claims losses, are particularly well suited to insurance-linked securities Vietnam structures because they avoid the lengthy loss adjustment process that indemnity-based triggers require, delivering liquidity to affected insurers and, indirectly, policyholders far faster after a typhoon or flood event.
Designing a credible parametric index for Vietnam requires reliable, independently verifiable meteorological and hydrological data sources, and structuring counsel should confirm early which data provider’s measurements will govern trigger determination, since disputes over trigger data can undermine investor confidence in insurance-linked securities Vietnam instruments as effectively as any legal defect in the transaction documents.
Basis risk, the mismatch between actual insured losses and the parametric trigger’s payout, is the central design trade-off. Insurance-linked securities Vietnam sponsors should be transparent with ceding insurers about expected basis risk levels, since a poorly calibrated parametric trigger can leave insurers under-compensated even after a qualifying event has clearly occurred.
Pricing for early insurance-linked securities Vietnam transactions is also likely to carry a novelty premium, reflecting investor unfamiliarity with Vietnam-specific catastrophe risk relative to more established markets such as Japan, the United States, or the Caribbean where catastrophe bond investors have decades of pricing data to draw on. Sponsors should expect initial transactions to price wider than an equivalent risk transfer in a mature ILS market, with pricing likely to tighten only as a track record of successfully triggered or successfully matured transactions accumulates.
5. What Would Need to Change for Domestic ILS Issuance
Three developments would meaningfully move insurance-linked securities Vietnam issuance from an offshore-only workaround toward a domestically issuable instrument: amendment of the Law on Insurance Business or implementing regulations to recognize a special purpose reinsurance vehicle structure, clearer foreign exchange guidance specifically addressing large contingent claims repatriation following a triggering catastrophe event, and development of independently verified meteorological and hydrological data infrastructure suitable for parametric trigger design.
None of these appear imminent, and insurers and reinsurers active in Vietnam should plan around the offshore structure as the realistic path for the foreseeable future rather than waiting for a domestic framework, an approach consistent with how Vietnam’s broader cross-border securitization market has developed in the absence of dedicated domestic legislation.
Regulators, including the State Bank of Vietnam on the foreign exchange side, will play a central role in whether insurance-linked securities Vietnam structures using offshore vehicles can scale beyond isolated pilot transactions, since foreign exchange clearance for contingent claims repatriation is likely to remain the single largest practical bottleneck regardless of insurance law reform progress.
Documentation complexity compounds cost for early transactions. Insurance-linked securities Vietnam structures require coordinated drafting across the offshore reinsurance agreement, the note issuance documents governed typically by New York or English law, and Vietnamese-law documentation covering the ceding insurer’s participation and any onshore regulatory filings, a three-jurisdiction drafting exercise that few Vietnamese insurers have executed before and that meaningfully extends transaction timelines relative to a purely domestic financing.
Investor education is a further practical hurdle worth planning for. Many capital markets investors active in the global catastrophe bond market have limited direct familiarity with Vietnamese natural catastrophe modeling, and arrangers should expect early insurance-linked securities Vietnam roadshows to spend disproportionate time explaining basic exposure geography, historical loss patterns, and the meteorological data infrastructure supporting any proposed parametric trigger, rather than assuming investors already understand the underlying risk the way they would for a more established peril region.
6. Basis Risk in Parametric Structures and Investor Communication
Parametric insurance-linked securities pay out based on the measured characteristics of a triggering event, such as wind speed or rainfall at defined reference points, rather than on the insured party’s actual verified loss, and this design choice creates basis risk: the possibility that the parametric payout does not match the actual economic loss suffered. Sponsors structuring a Vietnam-linked catastrophe bond around parametric triggers should model basis risk explicitly and communicate it clearly to both the ultimate risk-bearing entity and prospective investors.
Basis risk can run in either direction: a trigger may fire and require a payout even where actual losses were modest, or a genuinely severe event may fail to breach the specific parametric threshold if the reference stations or measurement points do not fully capture the geographic pattern of the actual damage. Sponsors can reduce, though not eliminate, this risk by using a denser network of reference stations or a blended index combining several measurement approaches, at the cost of a more complex and expensive structure to build and calibrate.
Investor communication about basis risk should be explicit and quantified where possible, since sophisticated catastrophe bond investors are accustomed to evaluating basis risk as a standard part of parametric structures, but a Vietnam-linked transaction without an established track record needs to work harder to build investor confidence in the specific trigger design and historical back-testing used to calibrate it, given the absence of a deep prior issuance history for Vietnamese catastrophe exposure.
Structure Your Catastrophe Risk Transfer With IVLF
Frequently Asked Questions
Can insurance-linked securities be issued directly out of Vietnam today?
No. Domestic issuance is not currently available, which is why sponsors use offshore SPV structuring as the practical workaround to access catastrophe risk transfer for Vietnamese exposure.
Why can’t Vietnamese insurers use a domestic special purpose vehicle for catastrophe bonds?
Regulatory and foreign exchange barriers currently prevent domestic ILS issuance, requiring insurers and reinsurers to route the risk transfer through an offshore vehicle governed by a jurisdiction with an established ILS framework.
What kind of trigger is typically used for Vietnamese catastrophe risk transfer?
Parametric triggers suited to Vietnam’s typhoon and flood exposure are commonly used, since they allow for faster claims settlement than indemnity-based triggers, though they introduce basis risk that needs to be clearly communicated to investors.
What is basis risk in a parametric catastrophe bond structure?
Basis risk can run in either direction: a trigger may fire and require payout even where actual losses were modest, or a genuinely severe event may fail to breach the specific parametric threshold, so investors need this risk explained and quantified upfront.
Insurance-linked securities Vietnam structuring requires coordinating insurance regulation, foreign exchange control, and offshore vehicle law simultaneously. IVLF advises insurers, reinsurers, and sponsors as a structured finance law firm Vietnam catastrophe risk transfer participants engage with, focusing on the offshore SPV structuring and basis risk disclosure that make a parametric transaction defensible to sophisticated investors. Contact IVLF to structure your catastrophe risk transfer.
This article is provided for general information only and does not constitute legal advice for any specific case. Regulations may change – please consult a qualified professional before acting. Should further analysis be required, please contact one of our lawyers below.