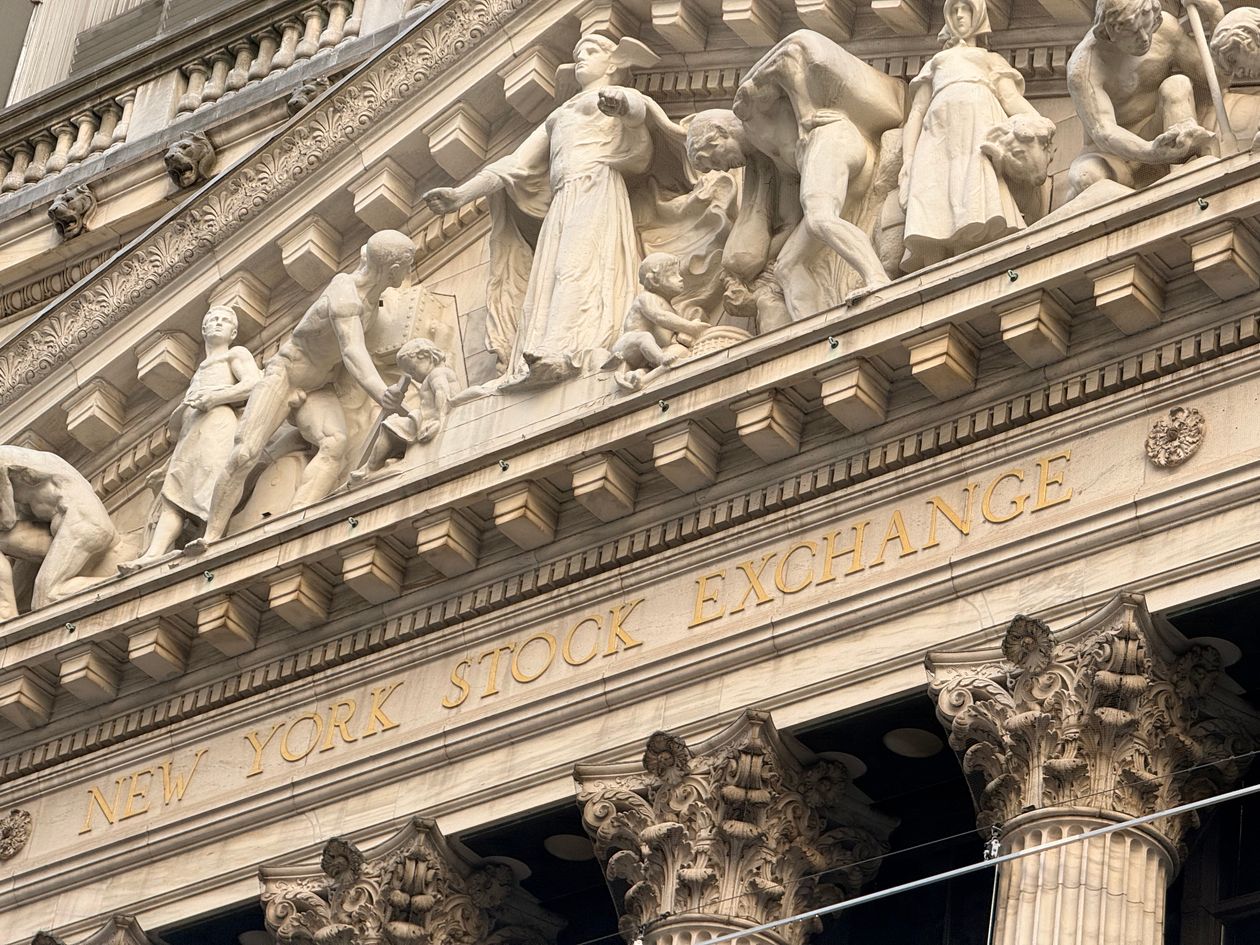
A US listing is the most demanding capital markets journey a Vietnamese company can attempt – and after VinFast reached Nasdaq, every ambitious board wants to know the real paths. Here they are, with the costs the pitch decks omit.
The three paths to a US listing
Traditional IPO
An offshore holding company above the Vietnamese business files with the SEC and lists on NYSE or Nasdaq. Maximum credibility, full underwriting support, deepest scrutiny – the route for issuers with scale and multi-year preparation.
De-SPAC merger
Merging into a listed special-purpose acquisition company delivers a US listing faster – VinFast’s route – but the speed is partly illusory: SEC review still applies, redemptions can shrink expected proceeds sharply, and post-merger share performance punishes weak preparation. A de-SPAC compresses the calendar, not the readiness requirement.
ADR programmes
American depositary receipts let US investors hold an existing listed stock without a full US listing – a stepping stone that builds familiarity, closely related to the depository receipt structures we cover separately.
What the SEC journey demands
- 01
Strategy & ScreeningTarget search, teasers and preliminary valuation
- 02
Due DiligenceLegal, tax, UBO and licensing review of the target
- 03
StructuringSPA terms, price mechanism and estimated-value dossier
- 04
ApprovalsM&A approval, merger filing and sector consents
- 05
Signing to ClosingEscrow, CPs, payment routing and integration
Financials under US GAAP or IFRS audited by a PCAOB-registered firm – often the single longest workstream. Internal controls that survive SOX testing. Disclosure drafted for the world’s most litigious market, where class actions follow stock drops as reliably as weather. And a Vietnamese structural layer: the offshore vehicle, outward investment approvals and foreign ownership analysis must all be in place before the US workstreams even matter – the architecture our offshore listing comparison maps venue by venue.
Costs and the honest go/no-go test
Expect preparation and execution to consume several million dollars, then several million more each year in audit, legal, insurance and investor relations. The go/no-go test is brutal but simple: does the valuation premium a US listing buys exceed those costs by enough to matter, and can management run a US-reporting company while still running the business? For a handful of Vietnamese issuers the answer is yes; for most, Hong Kong, Singapore or a strong domestic IPO delivers more value per dollar of pain.
Lessons the VinFast path teaches
- 01
Strategy & ScreeningTarget search, teasers and preliminary valuation
- 02
Due DiligenceLegal, tax, UBO and licensing review of the target
- 03
StructuringSPA terms, price mechanism and estimated-value dossier
- 04
ApprovalsM&A approval, merger filing and sector consents
- 05
Signing to ClosingEscrow, CPs, payment routing and integration
The first Vietnamese company on Nasdaq proved the structural path works: a Singapore holding company, a de-SPAC merger, and a US listing completed. It also demonstrated the fine print – heavy redemptions cut the cash raised, and post-listing volatility showed how unforgiving US markets are about float and coverage.
The transferable lessons: build the offshore structure years early; treat the SPAC route as a listing mechanism, not a fundraising guarantee; size the free float for real liquidity; and invest in investor relations before the bell rings, not after the first earnings miss.
For most Vietnamese issuers, the strategic takeaway is sequencing – prove the story on a domestic or regional listing first, build international reporting muscle, then attempt the US listing from strength. The companies that skip steps pay for them publicly.
Maintaining the listing: year two and beyond
The bell-ringing photo ages fast. From year two, a US listing means quarterly reporting cadences that dictate the management calendar, annual internal-control audits, proxy seasons, and continuous disclosure judgement calls where wrong answers carry personal liability for directors and officers.
Insurance mitigates but does not remove the exposure, and D&O premiums for newly listed emerging-market issuers are themselves a budget line worth negotiating early. Companies that build a genuine disclosure committee – counsel, finance, investor relations meeting on a rhythm – handle this well. Companies that treat US obligations as an annual scramble become enforcement statistics. The US listing rewards operational discipline more than it rewards ambition.
US Listing for Vietnamese Companies: IPO US, SPAC and ADR
US listing Vietnamese companies may be pursued through an IPO US, a SPAC Vietnam transaction or an ADR Vietnam programme. Each structure differs in cost, speed and investor profile.
US capital markets Vietnam access requires SEC compliance and quality governance. Companies should evaluate fit before committing to a route.
US listing: frequently asked questions
How long from decision to trading?
Twenty-four to thirty-six months for a traditional route including Vietnamese restructuring; a de-SPAC can compress the final phase but not the preparation.
Do US rules replace Vietnamese ones?
No – they stack. The Vietnamese operating companies keep every domestic obligation while the listed parent adds SEC duties. Two compliance stacks, one management team.
Who should be in the room first?
Auditor, US counsel, Vietnamese counsel and a banker – together, because sequencing failures between the four are where years disappear. Our capital markets team coordinates the Vietnamese side of exactly this table; SEC materials are published at sec.gov.
Or contact us directly:
Contact IVLF LawyerCompany Formation Services – IVLF Advisors
This article is provided for general information only and does not constitute legal advice for any specific case. Regulations may change – please consult a qualified professional before acting. Should further analysis be required, please contact one of our lawyers below.